EPF Wage Ceiling Revised from ₹15,000 to ₹25,000: Complete HR, Payroll & Finance Compliance Checklist for 2026.
EPF wage ceiling rises from ₹15,000 to ₹25,000 effective 17 September 2026. Explore the impact on HR, payroll, EPS, EDLI, ECR, contractors and finance teams with an implementation checklist.EPF wage ceiling rises from ₹15,000 to ₹25,000 effective 17 September 2026. Explore the impact on HR, payroll, EPS, EDLI, ECR, contractors and finance teams with an implementation checklist.
EPF Wage Ceiling Revised from ₹15,000 to ₹25,000: Complete HR, Payroll & Finance Compliance Checklist for 2026
Effective 17 September 2026 | Essential guidance for HR, Payroll, Finance, Compliance & Business Leaders
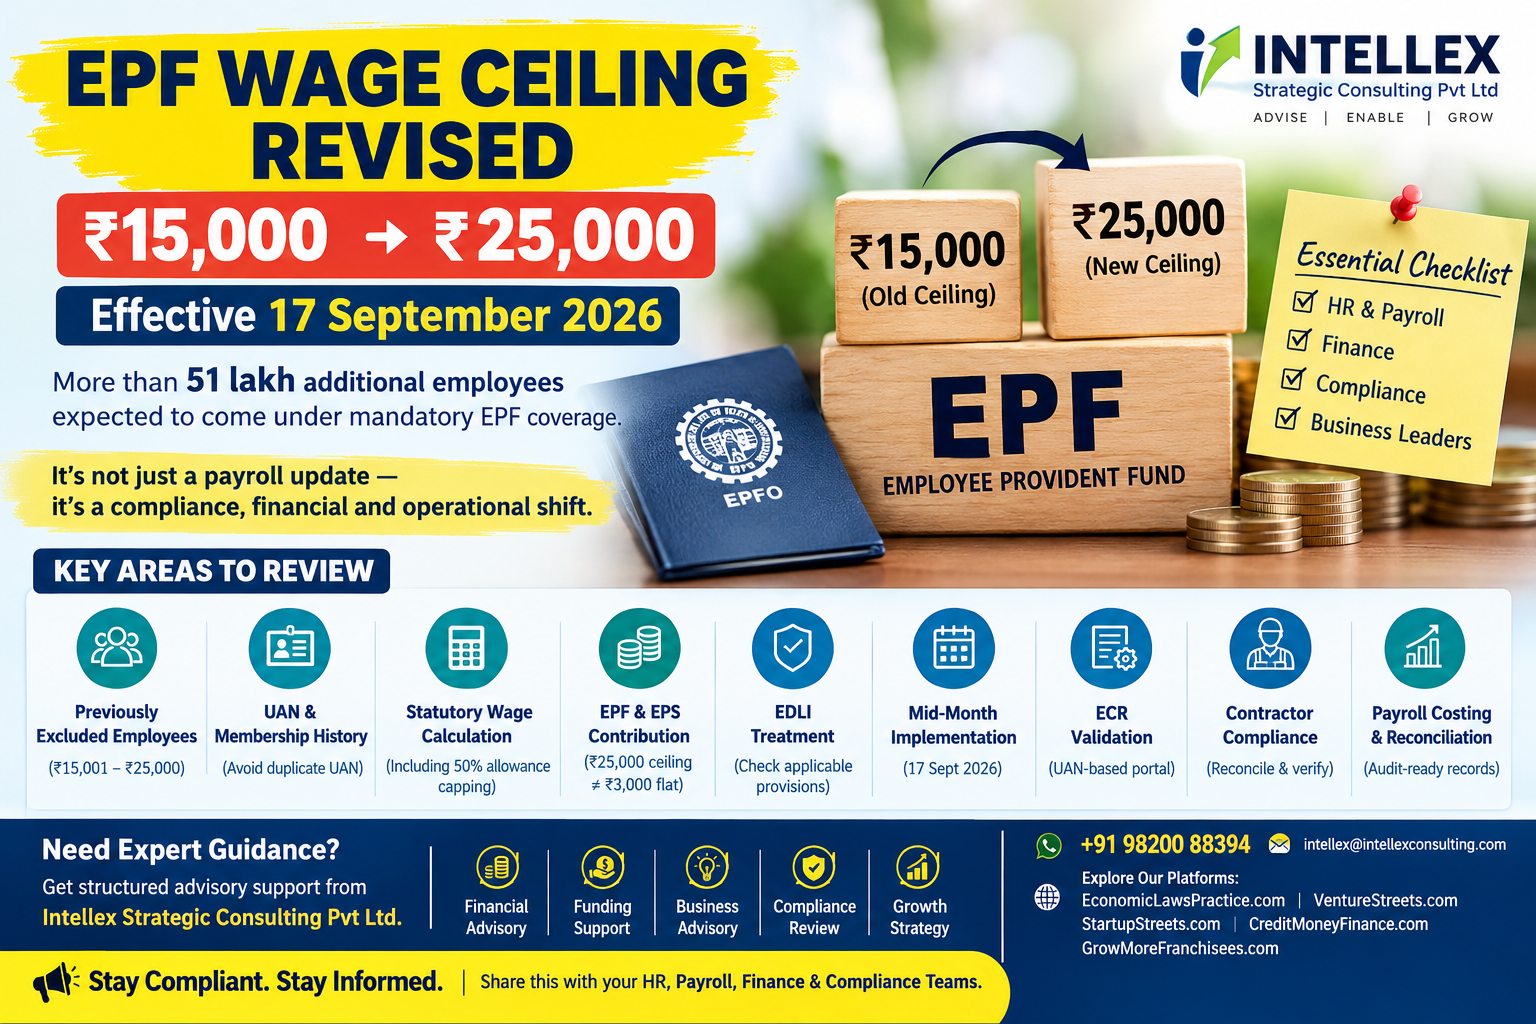
India’s EPFO framework has undergone a significant change with the revision of the statutory wage ceiling for mandatory EPF coverage from ₹15,000 to ₹25,000 per month, effective 17 September 2026.
The Government has stated that the revision is expected to bring more than 51 lakh additional employees within mandatory EPFO coverage, particularly employees in the ₹15,000–₹25,000 monthly wage range who were previously outside mandatory coverage because of the earlier ceiling.
For organisations, however, this is not simply a matter of changing ₹15,000 to ₹25,000 in a payroll configuration screen.
The change potentially affects:
- Employee eligibility and EPF membership
- Payroll master data
- Employee and employer contributions
- EPS allocation
- EDLI implications
- UAN mapping and member history
- ECR preparation and validation
- Contractor compliance
- Monthly payroll costing
- Employee communication
- Statutory reconciliation
- Internal and external audits
The key principle for implementation should therefore be:
Identify → Classify → Calculate → Configure → Test → Communicate → Reconcile → Document
1. What has changed?
The statutory EPF wage ceiling has increased from:
₹15,000 per month → ₹25,000 per month
The change is effective from 17 September 2026. The Government estimates that the revision will extend mandatory EPFO coverage to more than 51 lakh additional employees.
This is particularly relevant for employees whose wages fall within the newly covered band.
Illustrative impact
| Monthly statutory wage | 12% employee contribution |
|---|---|
| ₹15,000 | ₹1,800 |
| ₹20,000 | ₹2,400 |
| ₹25,000 | ₹3,000 |
Accordingly, ₹25,000 is a ceiling for statutory coverage/contribution purposes; it is not a universal flat ₹3,000 deduction for every employee.
The actual contribution must be determined employee-wise under the applicable EPF rules and wage definition.
For an employee whose statutory contribution was previously capped at ₹15,000 and is now calculated up to ₹25,000, the difference in the employee-side contribution can be as much as ₹1,200 per month, with a corresponding employer-side impact where applicable.
2. Mid-Month Implementation: The September 2026 Challenge
One of the biggest practical issues is the effective date.
The revised ceiling applies from 17 September 2026, which falls in the middle of the payroll month.
Therefore, HR and payroll teams should avoid creating an arbitrary formula such as:
₹15,000 ceiling for 1–16 September + ₹25,000 ceiling for 17–30 September
unless such treatment is specifically supported by EPFO’s applicable processing instructions.
The government notification establishes the revised ceiling and effective date, but payroll teams should carefully verify any subsequent EPFO instructions concerning September 2026 ECR processing, contribution treatment and day-wise computation.
Recommended approach
Before finalising September payroll:
- Review the official notification.
- Check the latest EPFO employer circulars/advisories.
- Check ECR portal validation requirements.
- Confirm the treatment with your payroll software provider.
- Document the methodology adopted.
- Avoid unsupported manual proration.
Do not let an internally created payroll formula become a statutory assumption.
3. Ceiling Does Not Mean Flat ₹3,000 Deduction
A common misunderstanding is:
“EPF ceiling is ₹25,000, therefore everyone pays ₹3,000.”
That is incorrect as a general proposition.
The 12% employee contribution illustration is:
- ₹15,000 × 12% = ₹1,800
- ₹20,000 × 12% = ₹2,400
- ₹25,000 × 12% = ₹3,000
Therefore, payroll configuration must determine the applicable statutory wage and contribution rather than applying a blanket ₹3,000 deduction.
This distinction is particularly important when organisations have:
- Different salary structures
- Variable allowances
- Employees with different membership histories
- Voluntary higher-wage contributions
- Existing EPF members
- Newly enrolled employees
4. Revisit the “Excluded Employee” Population
This is likely to be one of the most important HR exercises.
Organisations should generate a list of employees who were previously excluded from mandatory EPF coverage because their relevant wages exceeded the previous ₹15,000 ceiling, but now fall within the revised ceiling.
The newly relevant population may include employees in the:
₹15,001–₹25,000 wage range
The Government specifically stated that employees in this range will now come within the statutory social-security framework, subject to the applicable scheme provisions.
HR should therefore identify:
- Employees previously marked as excluded
- Employees who joined at wages above ₹15,000
- Employees currently earning between ₹15,000 and ₹25,000
- Employees with existing UANs
- Employees with previous PF service
- Employees with previous EPS membership
- Employees whose employment history needs to be linked
Important:
Do not automatically create a new UAN for an employee simply because the employee is being brought into payroll coverage.
First check whether the employee already has a UAN/PF membership history.
The objective should be correct mapping and continuity of membership, not duplicate creation.
5. “Once a Member, Always a Member” — Check Membership History
Payroll teams should not assume that an employee becomes exempt merely because current wages exceed ₹25,000.
An employee’s existing EPF membership status and applicable scheme provisions need to be examined.
Therefore, the payroll master should distinguish between:
- New employees
- Existing EPF members
- Previously excluded employees
- Employees with previous UANs
- Employees transferring between establishments
- Employees with EPS history
The question is not simply:
“What is the employee’s salary today?”
It is also:
“What is the employee’s EPF membership history and what rules apply to that employee?”
This is why HR should review UAN, previous employment and PF/EPS history before changing the employee’s statutory status.
6. Recheck the Definition of “Wages”
This is an area where payroll configuration requires particular attention.
The statutory wage test should not be based blindly on a company’s internal salary component called:
Basic + DA
Payroll and compliance teams should examine the applicable statutory definition of wages and the treatment of allowances, including the relevant statutory framework concerning allowances and the applicable 50% principle.
Therefore, organisations should map:
Salary Components → Statutory Wage Definition → EPF Eligibility → Contribution Calculation
rather than:
Basic Salary → Automatic EPF Decision
Payroll audit questions
Ask:
- Which salary components are included?
- Which components are excluded?
- How are allowances treated?
- Is the 50% statutory framework being considered where applicable?
- Is the payroll system using the correct wage base?
- Are variable components being handled correctly?
- Does the configuration match the organisation’s statutory interpretation?
This review should be documented for audit purposes.
7. EPS Allocation Must Be Revalidated
The revised ceiling also has implications for the employer-side allocation toward the Employees’ Pension Scheme (EPS), subject to the applicable eligibility and scheme provisions.
EPFO/PIB information released following the revision indicates that, with the pensionable wage ceiling at ₹25,000, the maximum employer pension contribution at 8.33% would be approximately ₹2,083 per month, compared with ₹1,250 under the ₹15,000 ceiling.
Illustration
₹25,000 × 8.33% ≈ ₹2,083
This means payroll systems should not merely increase the PF ceiling and assume that every other contribution component will automatically be correct.
Review:
- EPS eligibility
- Pension flag
- Employer contribution split
- EPS wage
- EPF wage
- Employee membership history
- Applicable rounding rules
8. EDLI: Do Not Assume Automatic Scaling
EDLI is another area that requires careful validation.
Although the revised EPF framework expands social-security coverage, organisations should not automatically assume that every EDLI parameter, assurance limit or payroll calculation changes simply because the EPF wage ceiling has increased.
Payroll and compliance teams should verify the specific statutory/EPFO provisions applicable to EDLI and any corresponding amendments or processing instructions.
In other words:
EPF ceiling change ≠ automatic assumption that every EDLI parameter has changed identically.
This is an important control point for payroll configuration.
9. ECR Validation: Small Data Errors Can Become Large Compliance Problems
The Electronic Challan-cum-Return (ECR) process requires accurate employee-level data.
EPFO’s employer portal currently operates with a UAN-based ECR format, making accurate member identification and mapping particularly important.
Before filing, payroll teams should validate:
- UAN
- Employee name
- Date of birth
- Gender
- Aadhaar/KYC status where applicable
- EPF wage
- EPS wage
- Contribution amounts
- Pension eligibility/flags
- Joining date
- Exit date, where applicable
- Previous membership
- New-member status
- Contribution period
Recommended control
Run a pre-ECR validation report before uploading the monthly return.
The objective should be to identify exceptions before submission rather than discovering them after rejection or reconciliation differences.
10. Contractor and Third-Party Payroll Compliance
The impact does not stop with employees directly appearing on the company’s payroll.
Principal employers should review contractors and outsourced workforce arrangements where EPF obligations apply.
Finance + HR + Procurement should jointly review:
- Contractor employee lists
- UAN details
- EPF registration
- ECR filings
- Wage data
- Contribution challans
- Employee-wise remittances
- Contractor invoices
- Statutory compliance certificates
- Contractual indemnity clauses
A contractor invoice should not be treated as proof of statutory compliance.
Where applicable, organisations should reconcile:
Contractor Payroll → ECR → Challan → Invoice → Attendance/Manpower Records
This creates a stronger audit trail.
11. Finance Impact: Reforecast Payroll Cost
The revision can increase statutory employment costs for affected employees.
Finance teams should therefore quantify:
Direct impact
- Employee contribution
- Employer contribution
- EPS allocation
- Other applicable statutory components
Indirect impact
- Payroll processing cost
- Contractor cost
- CTC implications
- Employee communication
- Payroll-system modifications
- Compliance review
- Potential arrears/reconciliation
- Additional administrative workload
Suggested financial exercise
Prepare an employee-wise impact report:
| Category | Employee Count | Previous PF | Revised PF | Incremental Monthly Cost |
|---|---|---|---|---|
| Below ₹15,000 | — | — | — | — |
| ₹15,001–₹20,000 | — | — | — | — |
| ₹20,001–₹25,000 | — | — | — | — |
| Existing members above ₹25,000 | — | — | — | — |
This allows Finance to quantify the actual impact instead of relying on a company-wide assumption.
12. Employee Communication Is Essential
A statutory payroll change can directly affect employee take-home pay.
For newly covered employees, explain:
- Why EPF is being deducted
- Effective date
- Employee contribution
- Employer contribution
- EPS implications, where applicable
- UAN requirements
- Nomination/KYC requirements
- How the deduction will appear on the payslip
A simple FAQ can prevent significant confusion.
Example employee questions
“Why has PF started being deducted from my salary?”
Because the statutory wage ceiling for mandatory EPF coverage has increased from ₹15,000 to ₹25,000 effective 17 September 2026, bringing additional employees within mandatory coverage, subject to the applicable scheme provisions.
“Why has my take-home salary changed?”
Because the employee’s statutory PF contribution may now be applicable or may increase depending on the applicable wage and membership rules.
“Will my employer also contribute?”
Employer-side statutory contributions apply according to the applicable EPF/EPS provisions.
13. Payroll System Configuration Checklist
Before going live, Payroll/HRIS teams should review:
☐ Wage ceiling master
☐ EPF eligibility logic
☐ Excluded-employee logic
☐ New-member identification
☐ Existing UAN mapping
☐ EPF wage calculation
☐ EPS wage calculation
☐ Employer contribution split
☐ EDLI configuration
☐ Rounding rules
☐ Mid-month September treatment
☐ ECR file generation
☐ ECR validation
☐ Payslip presentation
☐ Arrear/reprocessing logic
☐ Contractor payroll integration
☐ Audit reports
Do not make the production configuration change before testing the complete payroll-to-ECR workflow.
14. The Recommended Implementation Framework
Organisations can use the following eight-step framework:
IDENTIFY
Identify employees potentially affected by the revised ceiling.
CLASSIFY
Classify them according to:
- Existing EPF member
- New EPF member
- Previously excluded employee
- EPS status
- Wage category
CALCULATE
Calculate statutory wages and applicable contributions.
CONFIGURE
Update payroll and HRIS rules.
TEST
Run parallel calculations and test ECR output.
COMMUNICATE
Explain the change to employees and relevant contractors.
RECONCILE
Reconcile:
Payroll → ECR → Challan → General Ledger → Contractor Records
DOCUMENT
Maintain:
- Configuration approvals
- Payroll test results
- Employee classification
- ECR validations
- Reconciliation reports
- Management approvals
- EPFO communications/advisories relied upon
15. Management Dashboard: What CFOs, CHROs & CEOs Should Ask
Management does not need to examine every payroll record personally, but should ask the right questions.
HR
How many previously excluded employees are now potentially covered?
Payroll
Has the new wage ceiling been configured and tested?
Finance
What is the incremental monthly employer cost?
Compliance
Are UAN, EPS and ECR validations complete?
Procurement
Have contractor PF records been reconciled?
IT/HRIS
Has the payroll configuration been tested without affecting other statutory calculations?
Internal Audit
Can we demonstrate how every affected employee was classified and calculated?
These questions convert the regulatory change into a manageable internal control process.
16. Key Takeaway for HR, Payroll & Finance
The EPF ceiling revision from ₹15,000 to ₹25,000 is a statutory change with payroll, financial, employee and compliance consequences.
The most important mistake would be to treat it as a single-field payroll update.
The better approach is:
Wages → Eligibility → Membership → UAN → EPF → EPS → EDLI → ECR → Payroll → Finance → Reconciliation → Audit
The Government’s announcement confirms the scale of the change, with more than 51 lakh additional employees expected to enter mandatory EPFO coverage.
For September 2026 in particular, organisations should pay close attention to the effective date, official EPFO processing instructions and ECR requirements before finalising their methodology.
How Intellex Strategic Consulting Pvt Ltd Can Help
Intellex Strategic Consulting Pvt Ltd supports businesses, startups and growing organisations with strategic financial, funding and business advisory requirements.
For organisations dealing with regulatory changes such as the EPF wage ceiling revision, Intellex can support management teams with structured reviews covering:
HR & Payroll Compliance Review
Review of affected employee populations, payroll calculations and statutory processes.
Financial Impact Assessment
Employee-wise and organisation-level assessment of potential incremental employment costs.
Compliance & Process Review
Identification of process gaps, documentation requirements and reconciliation controls.
Business & Financial Advisory
Support for businesses evaluating funding, working capital, project finance and strategic financial requirements.
Funding & Capital Advisory
Assistance across debt funding, equity funding, project finance, structured finance, startup fundraising and related financial requirements.
Strategic Business Support
Advisory support for businesses looking at growth, acquisitions, financial restructuring and strategic expansion.
Intellex Strategic Consulting Pvt Ltd — helping businesses navigate financial, funding and strategic challenges with structured advisory support.
Connect with Intellex Strategic Consulting Pvt Ltd
📱 WhatsApp: +91 98200 88394
📧 Email: intellex@intellexconsulting.com
Explore our platforms:
EconomicLawsPractice.com — Legal, regulatory and business-law focused information
VentureStreets.com — Venture, investment and entrepreneurial ecosystem
StartupStreets.com — Startup and entrepreneurship resources
CreditMoneyFinance.com — Credit, finance and funding resources
GrowMoreFranchisees.com — Franchise and business-growth opportunities
Final Compliance Reminder
EPF compliance is not just about making a deduction.
It is about ensuring that:
The right employee is identified → the right wage is determined → the right contribution is calculated → the right UAN is mapped → the right ECR is filed → and the entire process can be demonstrated during an audit.
Stay compliant. Stay informed. Build stronger payroll controls.
📢 Share this article with your HR, Payroll, Finance, Accounts, Compliance and Business teams.
Compliance Today Secures Protection Tomorrow.
This article is intended for general compliance awareness and business information. Organisations should verify the latest EPFO notifications, circulars and ECR processing instructions applicable to their specific circumstances before implementing payroll changes.
EconomicLawsPractice.com
More Featured Articles:
GST Advisory Services by IntellexCFO.com to indian business community.