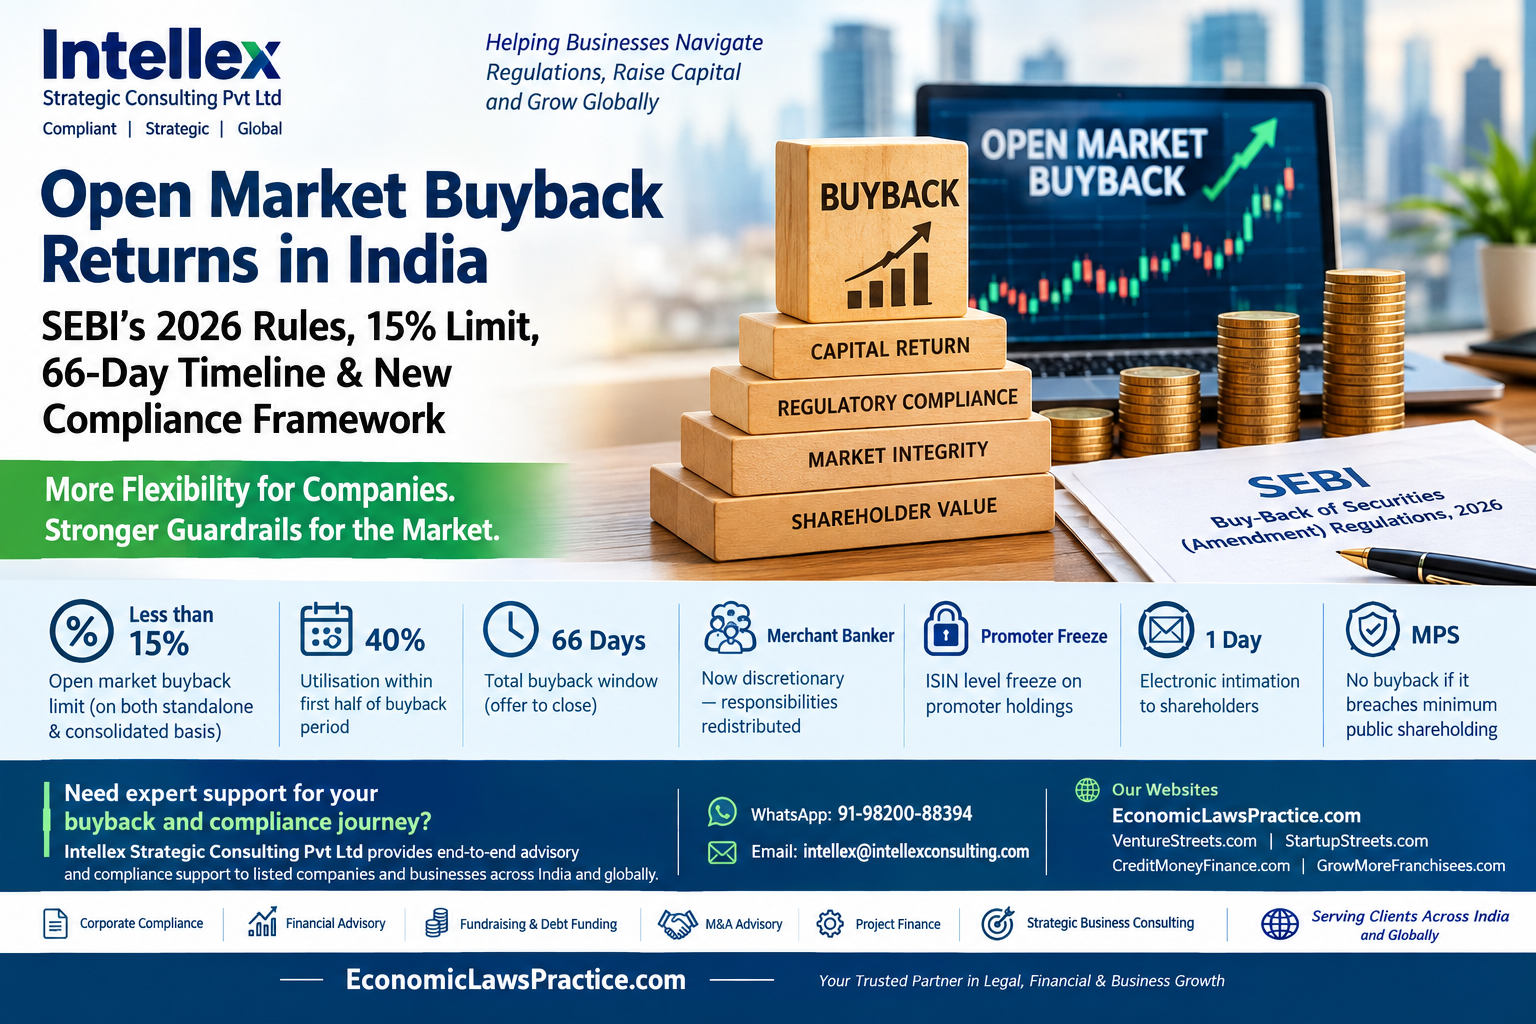
Open Market Buyback Returns in India: SEBI’s 2026 Buyback Rules, 15% Limit, 66-Day Timeline & New Compliance Framework.
SEBI’s 2026 Buyback Regulations revive open market buybacks from August 1, 2026. Understand the 15% limit, 40% utilisation rule, 66-day timeline, promoter freeze, MPS safeguard and compliance responsibilities.
Open Market Buyback Is Back – And This Time With Stronger Guardrails
SEBI’s 2026 Buyback Regulations Bring Back the Stock-Exchange Route With Tighter Compliance, Faster Timelines and Greater Accountability
A significant development has taken place in India’s securities-market regulatory framework that listed companies, promoters, company secretaries, compliance officers, statutory auditors, secretarial auditors, legal advisers and other corporate professionals need to understand carefully.
The Securities and Exchange Board of India (Buy-Back of Securities) (Amendment) Regulations, 2026 were notified on 1 July 2026 and came into force from 1 August 2026. The amendments have effectively brought back the open market buyback route through stock exchanges, subject to a substantially strengthened compliance framework.
The return of this mechanism is particularly important because open-market buybacks through stock exchanges had ceased to be available from April 1, 2025, following the earlier phase-out.
SEBI’s 2026 framework does not simply restore the earlier mechanism. It introduces a series of safeguards covering the quantum of buyback, utilisation of funds, timelines, promoter trading restrictions, minimum public shareholding, shareholder communication and allocation of responsibilities among the company, auditors, compliance officers, stock exchanges and other intermediaries.
The result is a framework that offers listed companies another capital-return mechanism, but with a much more structured compliance architecture.
What Is an Open Market Buyback?
A buyback is a transaction through which a company purchases its own shares or specified securities from shareholders.
Broadly, listed companies can undertake buybacks through different mechanisms permitted under the regulatory framework.
The two routes that are particularly relevant are:
- Tender offer buyback
- Open market buyback through the stock exchange
Under the open-market mechanism, the company purchases its shares through the stock exchange rather than inviting shareholders to tender a specified number of shares at a fixed offer price.
This distinction has important consequences.
An open-market buyback operates through market transactions and therefore involves considerations relating to price discovery, trading behaviour, promoter restrictions, utilisation of the buyback amount and market integrity.
SEBI’s 2026 framework seeks to provide this flexibility while addressing the concerns that had previously surrounded the mechanism.
Why Was the Open Market Route Discontinued?
The history of open-market buybacks is important for understanding why the 2026 framework contains stronger safeguards.
One of the concerns associated with the stock-exchange route was that, under normal price-time priority mechanisms, shareholders did not necessarily have an equal practical opportunity to participate.
A shareholder wishing to sell into a buyback could find that the company’s earmarked purchase quantity was exhausted before that shareholder’s order was executed.
This created concerns around equitable participation.
There were also significant changes in the tax treatment of buybacks over the years.
The tax framework has now changed again from April 1, 2026. Under Section 69 of the Income-tax Act, 2025, consideration received by a shareholder when a company purchases its own shares is generally dealt with under the capital-gains framework. For promoter shareholders, additional tax provisions can apply.
This shift in tax incidence is an important part of the broader environment in which the open-market mechanism has been reintroduced.
Why Has SEBI Brought It Back?
The 2026 changes can broadly be viewed as an attempt to balance two objectives:
Flexibility for listed companies
Companies with surplus cash and appropriate financial capacity may want to return capital to shareholders without necessarily undertaking a fixed-price tender offer.
Investor and market protection
At the same time, an open-market buyback can potentially affect market liquidity, price formation and promoter activity.
SEBI has therefore attached specific safeguards to the revived mechanism.
The regulator’s consultation process specifically considered the duration, utilisation requirement, merchant banker role, promoter holdings, compliance certifications and other procedural matters before the final amendments were notified.
1. Open Market Buyback Is Now Subject to a Less-Than-15% Limit
One of the most important provisions relates to the size of an open-market buyback.
With effect from August 1, 2026, an open-market buyback through stock exchanges must be less than 15% of the paid-up capital and free reserves of the company.
Importantly, the calculation is based on both standalone and consolidated financial statements.
This is significant from a compliance perspective.
The finance and company-secretarial teams cannot simply calculate the permissible amount using one set of financial statements and proceed.
The appropriate financial information needs to be evaluated carefully before the Board considers the proposal.
Why this matters
The quantum calculation should form part of the initial feasibility assessment covering:
- Paid-up capital
- Free reserves
- Standalone financial statements
- Consolidated financial statements
- Existing capital structure
- Debt position
- Statutory restrictions
- Minimum public shareholding
- Other applicable buyback conditions
A buyback proposal should therefore be treated as a structured corporate transaction rather than merely a treasury decision.
2. Tender Offer and Open Market Buyback Are Not the Same
The distinction between the two mechanisms becomes particularly important under the revised framework.
| Particular | Open Market Buyback | Tender Offer Buyback |
|---|---|---|
| Mechanism | Purchase through stock exchange | Shareholders tender shares |
| Permitted quantum | Less than 15% of paid-up capital and free reserves | Up to 25%, subject to applicable conditions |
| Price | Market-based | Fixed offer price |
| Execution | Stock exchange mechanism | Tender process |
| Small shareholder reservation | No equivalent 15% reservation | 15% reservation continues |
| Promoter participation | Promoter holdings are subject to freeze restrictions | Promoters may tender, subject to applicable rules |
| Maximum open period | 66 working days | Tendering period is substantially shorter |
| Price discovery | Market-driven | Offer price determined in advance |
The choice of route therefore requires careful consideration of the company’s objectives, capital structure, shareholder profile, market conditions and compliance requirements.
3. The 40% Utilisation Requirement
One of the important safeguards retained in the framework relates to utilisation of the amount earmarked for the buyback.
At least 40% of the amount earmarked for the buyback must be utilised during the first half of the specified buyback period.
The purpose is straightforward: a company should not announce a substantial buyback and then leave the market uncertain about whether meaningful purchases will actually take place.
SEBI’s consultation paper specifically considered retaining the 40% utilisation requirement in conjunction with the revised 66-working-day maximum duration.
Compliance implication
The company should establish internal monitoring mechanisms covering:
- Amount earmarked
- Amount actually utilised
- Number of shares purchased
- Average purchase price
- Remaining amount
- Remaining permissible quantity
- Daily exchange reporting
- First-half utilisation status
Treasury, finance, compliance and company-secretarial functions will therefore need to work closely throughout the buyback.
4. The Buyback Timeline Has Been Compressed
The revised framework places considerable emphasis on speed and certainty.
The open-market buyback must be completed within 66 working days from the date of opening of the offer.
The offer is also required to open within four working days of the public announcement.
This represents a significant change from the earlier environment, where companies could have substantially longer periods to complete the process.
SEBI’s consultation paper expressly observed that a six-month period could be relatively long and proposed a 66-working-day maximum period to facilitate timely implementation.
Practical message for companies
A buyback cannot be treated as a transaction that begins after the Board meeting.
The preparation needs to begin well before the approval date.
Documentation, financial calculations, regulatory checks, depository coordination, exchange requirements, shareholder data and professional responsibilities should be mapped in advance.
5. Merchant Banker Appointment Is Now Discretionary
Perhaps one of the most consequential practical changes is that appointment of a merchant banker for the buyback is no longer mandatory in the same manner as under the earlier framework.
The company can decide whether to appoint one.
This is intended to provide greater flexibility and potentially reduce transaction costs.
However, there is an important qualification.
Removing the mandatory merchant banker does not mean removing the underlying compliance responsibilities.
Instead, relevant responsibilities are redistributed among other participants.
SEBI’s consultation documents contemplated this redistribution, with functions being assigned to the company, secretarial auditor, statutory auditor, compliance officer and stock exchanges.
6. What Happens If There Is No Merchant Banker?
If the company chooses not to appoint a merchant banker, responsibilities that would otherwise sit with the merchant banker do not disappear.
They move to designated participants under the revised framework.
Company
The company assumes important responsibility for:
- Public announcement-related filings
- Accuracy of disclosures
- Adequacy and fairness of information
- Regulatory documentation
- Overall coordination of the buyback process
Secretarial Auditor
The Secretarial Auditor assumes enhanced responsibility relating to:
- Due diligence
- Compliance certification
- Verification of compliance with applicable requirements
Statutory Auditor
The Statutory Auditor has enhanced responsibilities relating to areas such as:
- Escrow arrangements
- Bank guarantee matters
- Relevant verification and oversight
- Applicable release/invocation processes
Stock Exchanges
Stock exchanges have defined responsibilities relating to matters such as:
- Sell-order adequacy
- Volume-Weighted Average Price certification
- Exchange-level processing and reporting
Compliance Officer
The Compliance Officer has an important role in areas including:
- Extinguishment/destruction-related compliance
- Presence/verification requirements
- Final compliance-related reporting
The practical consequence is important.
A company that chooses not to appoint a merchant banker does not get a “lighter” compliance process. It gets a different allocation of responsibilities.
7. Promoter Holdings Face an ISIN-Level Freeze
The promoter-related provisions represent another major investor-protection safeguard.
SEBI has introduced operational requirements for freezing promoter and promoter-group holdings, including holdings of their associates, at the ISIN level during the relevant buyback period.
SEBI issued a separate circular on July 21, 2026 operationalising this freezing mechanism.
The underlying objective is to prevent inadvertent or inappropriate promoter trading during the buyback process.
What does this mean for promoters?
Promoters need to consider the restriction before the buyback process reaches the approval stage.
Liquidity requirements, planned share transfers and other proposed transactions involving promoter holdings should be reviewed in advance.
The company will also need to coordinate appropriately with the depositories and other relevant stakeholders.
Tender offer distinction
The treatment is not identical under every buyback mechanism.
Under a tender offer, the framework provides for the relevant mechanism to enable promoters to tender shares, subject to the prescribed conditions.
Therefore, the promoter strategy needs to be evaluated together with the selected buyback route.
8. Electronic Shareholder Intimation Within One Working Day
Another important disclosure-related requirement is the electronic communication to shareholders.
Companies need to ensure that shareholders who held shares on the relevant announcement date are appropriately informed electronically within the prescribed timeline.
This creates an important operational dependency on shareholder records.
Why RTA data becomes important
Companies should ensure that:
- Email IDs are updated
- Shareholder records are accurate
- RTA data is reconciled
- Demat information is properly captured
- Corporate-action databases are current
A buyback therefore brings shareholder-data quality directly into the compliance workflow.
9. Minimum Public Shareholding Is a Pre-Approval Check
The revised framework specifically provides that a company cannot propose a buyback that would result in a breach of applicable Minimum Public Shareholding (MPS) requirements.
This is an important Board-level safeguard.
MPS should therefore not be checked only after the buyback has already been approved.
It needs to form part of the pre-Board feasibility analysis.
The company should model the effect of the proposed buyback on:
- Promoter shareholding
- Public shareholding
- Post-buyback capital
- Shareholding concentration
- Applicable MPS requirements
A transaction that looks financially attractive could still be structurally unavailable if it would create an MPS problem.
10. Tax Treatment Has Also Changed From April 1, 2026
The regulatory story cannot be understood separately from the tax changes.
From April 1, 2026, the Income-tax Act, 2025 provides for the difference between consideration received by a shareholder and the applicable acquisition cost to be treated as capital gains when a company purchases its own shares or specified securities.
The tax treatment therefore places the tax incidence on the shareholder rather than operating under the earlier company-level buyback tax framework.
There are additional provisions for promoter shareholders.
For promoters, the law provides for additional income tax over and above the tax otherwise payable on the capital gains, with rates depending on the nature of the gain and the promoter’s status.
Why this matters for a listed company
The tax treatment should be factored into shareholder communication and transaction planning.
Companies should ensure that their advisers examine:
- Resident shareholders
- Non-resident shareholders
- Promoter shareholders
- Capital-gains computation
- Applicable withholding requirements
- Cost of acquisition
- Treaty considerations, where applicable
- Relevant disclosures
The exact tax consequences can vary according to the shareholder’s circumstances.
11. A Buyback Is Now a Cross-Functional Compliance Project
The biggest practical lesson from the 2026 framework is that buyback compliance cannot sit with one department.
A successful transaction requires coordination between multiple functions.
Board and management
Responsible for strategic approval and oversight.
Finance and treasury
Responsible for:
- Funding availability
- Financial calculations
- Escrow arrangements
- Utilisation monitoring
- Capital structure analysis
Company Secretary and compliance team
Responsible for:
- Board processes
- Regulatory filings
- Stock exchange communication
- Disclosure compliance
- Timeline management
- Coordination with professionals
Secretarial Auditor
Responsible for enhanced due diligence and compliance certification where the merchant banker route is not used.
Statutory Auditor
Responsible for specified financial and escrow-related responsibilities.
RTA
Responsible for shareholder data and relevant corporate-action processes.
Depositories
Important for promoter holding freezes and related securities processing.
Stock Exchanges
Responsible for exchange-level processing and prescribed certifications.
The new regime therefore creates an ecosystem rather than a single-point compliance process.
12. The Strategic Decision: Merchant Banker or Internal Execution?
For companies considering an open-market buyback, one of the earliest decisions should be whether to appoint a merchant banker.
There is no universal answer.
The decision should be based on factors such as:
- Size of the buyback
- Complexity of the shareholder base
- Company’s internal compliance capabilities
- Experience of the management team
- Availability of qualified professionals
- Cost considerations
- Transaction timetable
- Regulatory complexity
- Existing relationship with professional advisers
Option A — Appoint a Merchant Banker
This can provide a central professional intermediary for the transaction and may simplify coordination.
Option B — Do Not Appoint a Merchant Banker
This can potentially reduce transaction costs but requires the company and designated professionals to absorb the responsibilities redistributed under the revised framework.
The second option should therefore not be viewed simply as a cost-saving exercise.
It is also a responsibility-allocation decision.
13. A Suggested Buyback Compliance Checklist
Before approving an open-market buyback, listed companies should consider creating a comprehensive checklist covering at least the following:
Corporate eligibility
☐ Verify statutory eligibility
☐ Verify fully paid-up securities
☐ Review debt and financial ratios
☐ Check restrictions arising from defaults
☐ Review previous buyback history
☐ Check applicable cooling-off period
Quantum
☐ Calculate paid-up capital
☐ Calculate free reserves
☐ Perform standalone calculation
☐ Perform consolidated calculation
☐ Confirm less-than-15% open-market ceiling
MPS
☐ Calculate current public shareholding
☐ Model post-buyback shareholding
☐ Confirm no MPS breach
Promoters
☐ Identify promoter and promoter-group holdings
☐ Identify relevant associates
☐ Map holdings by ISIN
☐ Coordinate with depositories
☐ Implement required freeze
Documentation
☐ Board documentation
☐ Public announcement
☐ Regulatory filings
☐ Stock exchange filings
☐ Escrow documentation
☐ Bank guarantee documentation, where applicable
☐ Shareholder communication
Professional appointments
☐ Decide whether to appoint merchant banker
☐ Secretarial Auditor responsibilities
☐ Statutory Auditor responsibilities
☐ Compliance Officer responsibilities
☐ RTA responsibilities
☐ Broker/exchange coordination
Execution
☐ Opening timeline
☐ Daily purchase monitoring
☐ 40% first-half utilisation monitoring
☐ VWAP monitoring/certification
☐ Sell-order monitoring
☐ Extinguishment process
☐ Final reporting
14. Open Market Buyback vs Tender Offer — Practical Perspective
The two routes serve different practical purposes.
An open-market buyback gives the company access to a market-based mechanism and allows purchases to take place through the stock exchange.
The tender route provides a more structured invitation to shareholders at a predetermined price and includes the prescribed small-shareholder reservation.
Therefore, the decision should be based on the company’s circumstances rather than simply selecting the route with the larger numerical limit.
A proper evaluation should consider:
Capital availability + shareholder profile + market liquidity + promoter participation + MPS + tax implications + compliance resources + transaction costs + desired timeline.
15. What This Means for Compliance Professionals
The reintroduction of open-market buybacks creates a significant area of work for corporate compliance professionals.
The opportunity is not merely in preparing documents.
There is scope for professional assistance across the entire transaction lifecycle:
- Buyback feasibility assessment
- Regulatory eligibility review
- Buyback route evaluation
- Board-process support
- Compliance checklists
- Public announcement support
- Regulatory filing coordination
- Promoter holding analysis
- ISIN-level freeze coordination
- Shareholder-data review
- RTA coordination
- Stock-exchange coordination
- Auditor coordination
- Transaction timetable management
- Compliance certification support
- Post-buyback compliance
- Extinguishment-related processes
- Final reporting
The expanded allocation of responsibilities makes coordination particularly important where a company elects not to appoint a merchant banker.
16. Why Companies Should Start Planning Before the Board Meeting
One of the most common mistakes in regulatory transactions is beginning the compliance exercise only after the Board has approved the proposal.
The 2026 framework makes early preparation even more important.
Before the Board considers the proposal, management should ideally have clarity on:
1. Is the company eligible?
2. What is the maximum permissible buyback amount?
3. Does the proposed transaction comply with MPS requirements?
4. Which route is appropriate?
5. Will a merchant banker be appointed?
6. Who will assume each responsibility if there is no merchant banker?
7. Are promoter holdings ready for the required freeze?
8. Are shareholder records and email IDs updated?
9. Are escrow and funding arrangements ready?
10. Can the company realistically execute the transaction within the prescribed timelines?
A properly prepared transaction can significantly reduce the risk of last-minute procedural complications.
17. The Bigger Picture
The 2026 amendments represent more than simply the return of an old buyback mechanism.
They reflect a broader regulatory approach:
Flexibility for companies — combined with stronger process discipline.
SEBI has made the merchant banker appointment discretionary, but redistributed responsibilities.
It has brought back the open-market mechanism, but introduced tighter controls.
It has permitted market-based purchases, but strengthened promoter restrictions.
It has provided companies with flexibility in capital allocation, but retained minimum utilisation requirements.
It has shortened the execution period, increasing the importance of advance planning.
The message for listed companies is therefore clear:
Buyback flexibility has returned — but compliance cannot be treated casually.
Intellex Strategic Consulting Pvt Ltd — Professional Support for Listed Companies and Businesses
Intellex Strategic Consulting Pvt Ltd provides professional advisory and consulting support to businesses across India and internationally.
For companies evaluating strategic financial, corporate, regulatory and business requirements, Intellex can provide professional support and coordination across relevant areas, including corporate compliance support, financial advisory, fundraising, debt funding, equity investment, project finance, M&A advisory, financial modelling and strategic business consulting.
For listed companies considering a buyback, capital restructuring or other strategic corporate transaction, professional preparation and coordination can be critical to keeping the transaction on schedule and ensuring that the relevant stakeholders understand their respective responsibilities.
Connect With Intellex Strategic Consulting Pvt Ltd
WhatsApp: 91-98200-88394
Email: intellex@intellexconsulting.com
Our Websites
EconomicLawsPractice.com
VentureStreets.com
StartupStreets.com
CreditMoneyFinance.com
GrowMoreFranchisees.com
Intellex Strategic Consulting Pvt Ltd
Professional Services firm providing services related to this article and a wide range of strategic business, financial and corporate requirements.
Serving clients across India and supporting international business requirements.
Final Takeaway
The return of the open-market buyback route is an important development for India’s listed-company ecosystem.
But the 2026 framework should not be viewed simply as a restoration of the old system.
The new framework combines:
Market-based buybacks + a less-than-15% limit + 40% utilisation discipline + 66-working-day completion + promoter holding freezes + MPS safeguards + electronic shareholder communication + redistributed professional responsibilities.
For listed companies considering a buyback during the second half of 2026 and beyond, the most important exercise is therefore not merely deciding whether to buy back shares.
It is determining how the buyback will be structured, who will perform each compliance function, and whether the entire transaction can be executed within the regulatory framework and prescribed timelines.
The opportunity is back.
The compliance responsibility is stronger than before.
This article is intended for general informational and professional awareness purposes. Buyback transactions involve company law, SEBI regulations, securities-market requirements and tax considerations. Companies should obtain transaction-specific professional advice and verify the regulations and applicable circulars in force at the time of undertaking a buyback.
EconomicLawsPractice.com
Major GST Compliance Overhaul Effective April 2026: What Businesses Must Act On in May.
ESOP Compliance in India: A Complete Guide for Compliance Professionals (2026 Edition).
How Businesses in the UAE Can Stay Ahead of Compliance Demands in 2026.
The Ultimate Guide to Company Registration in Dubai 2026: Benefits, Compliance, and Costs.
Ultimate Guide to Singapore Company Registration 2026: Rules, Costs, and Compliance.